Here you’ll find definitions of terms used on this website. Enter the term you want to search for in the box, or click on a letter to find terms beginning with that letter.

5 A B C D E F G H I J L M N O P R S T U V W Y Z

Below you'll find some frequently searched terms. Use the search box to find more

A report prepared by a company each year after its year end. It sets out what the company does, how it has performed over the year and its financial position.

The annual accounts will normally cover 12 months, but can be for a shorter or longer period. They typically include:

  • a financial summary
  • a Chairman’s statement covering issues such as performance, dividends, the company’s use of gearing etc.
  • a review by the fund manager of how the portfolio has performed, any changes that have been made and its prospects for the future
  • a corporate governance statement
  • a detailed set of financial statements

See also interim accounts and half yearly report
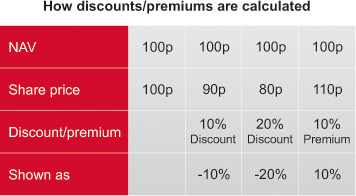
The amount, expressed as a percentage, by which an investment trust's share price is less than its net asset value per share. For example, if the net asset value is 100p and the share price is 90p, the shares are trading at a 10% discount. 

An illustration showing the calculation of a discount, typically used to explain the difference between a share price and net asset value.

Learn more about discounts and premiums

See premium.

Income from an investment in shares. Most, but not all, investment trusts pay dividends to their shareholders.

Dividends are usually paid according to a regular schedule: quarterly, semi-annually, annually, or occasionally monthly. Dividend income isn't guaranteed and may fall as well as rise.

See special dividend.

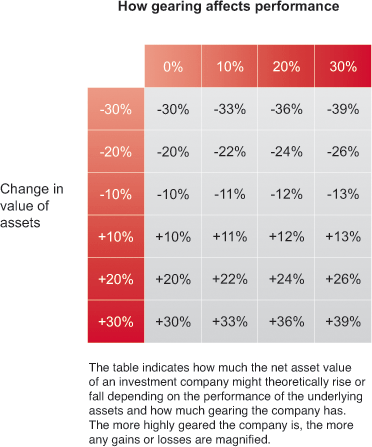
Gearing allows investment trusts (investment companies) to magnify income and capital returns, but can also magnify losses.

At its simplest, gearing means borrowing money to buy more assets in the hope the company makes enough profit to pay back the debt and interest and leave something extra for shareholders.

However, if the investment portfolio doesn’t perform well, gearing can increase losses. The more an investment trust gears, the higher the risk.

Investment trusts can usually borrow at lower rates of interest than you’d get as an individual. They can also gear in other ways: for example, by using derivatives or issuing special shares called zero dividend preference shares

Not all investment trusts use gearing, and most that do use modest levels. 

A company that doesn't sell products or services, but instead invests in a diversified portfolio of assets. By buying shares in the investment company on the stock exchange, investors can get exposure to the assets it invests in. 

Investment companies are sometimes called investment trusts, closed-ended funds or listed funds. 

Types of investment company listed on the London Stock Exchange include UK investment trusts, non-UK investment companies, venture capital trusts (VCTs) and real estate investment trusts (REITs).

The standard measure of performance for an investment trust, taking into account the change in share price over a period of time as well as all the dividends paid during that period. It is assumed that the dividends are reinvested at the time the shares are quoted ex dividend.

Share price total return takes into account the change in value of the underlying portfolio of the investment trust and any dividends paid, as well as the discount or premium at which the shares trade, and any change in discount or premium over the period.

Contrast this with the NAV total return, which only takes into account the change in value of the underlying portfolio of the investment trust and any dividends paid.

See share price, NAV total return and total return.

Tradable Instrument Display Mnemonics. A short, unique code used to identify UK-listed shares, commonly known as a "ticker".