

India investment trusts: Is the long-term story still intact after a difficult 2026?
India has been one of the world’s best-performing major equity markets over the past decade, supported by strong GDP growth, rising household wealth, digitalisation and expanding manufacturing. For UK investors, investment trusts remain one of the easiest ways to gain diversified exposure to the country’s long-term structural growth.
Sharesify podcast with James Thom of Aberdeen New India Investment Trust
However, after a spectacular rally between mid-2022 and late-2024, Indian equities have entered a much more challenging period.
Major UK investment trusts with Indian exposure
| Investment trust | Estimated India exposure | Investment style | Typical discount/premium* |
| JPMorgan India Growth & Income | ~100% | Large & mid-cap growth | ~5-8% discount |
| Ashoka India Equity | ~100% | High-quality businesses | Around NAV to small discount |
| Aberdeen New India | ~100% | All-cap active | ~7-10% discount |
| India Capital Growth | ~100% | Smaller companies | ~9-12% discount |
| Templeton Emerging Markets | ~20-30% | Emerging markets | Mid-single-digit discount |
| JPMorgan Emerging Markets | ~10% | Emerging markets | Small discount |
*Approximate mid-2026 trading ranges. Discounts fluctuate daily.
From boom to consolidation
Indian equities enjoyed one of their strongest periods on record between June 2022 and September 2024.
Several factors drove the rally:
- Strong corporate earnings growth
- Robust domestic retail investment inflows
- Manufacturing relocation away from China
- Government infrastructure spending
- Digital economy expansion
- Rising foreign institutional investment
During that period the Nifty 50 and Sensex repeatedly reached record highs, while mid-cap and small-cap shares substantially outperformed.
Then came consolidation
Rather than collapsing, the market largely moved sideways between roughly October 2024 and January 2026.
This 15-month consolidation allowed:
- valuations to cool
- earnings to catch up
- speculative excesses in smaller companies to unwind
- investors to reassess lofty expectations
Many investment trust managers argued this was a healthy pause following an exceptionally powerful bull market rather than the start of a structural bear market.
2026 has been more difficult
This year has seen:
- weaker foreign investor flows
- concerns about global tariffs
- higher US bond yields
- stronger sterling reducing GBP returns
- profit-taking after several exceptional years
Although local currency performance has generally proved more resilient, sterling investors have felt additional pressure from currency movements.
Why many managers remain optimistic
Despite recent weakness, fund managers continue highlighting several structural advantages.
Domestic consumption
Unlike many emerging markets, India is increasingly driven by domestic consumers rather than exports.
A growing middle class supports:
- banking
- insurance
- healthcare
- travel
- consumer brands
- technology services
Manufacturing opportunity
Global companies continue diversifying supply chains away from China.
India is benefiting from investment into:
- electronics
- semiconductors
- industrial manufacturing
- renewable energy
- infrastructure
Strong economic growth
Most economists continue expecting India to remain among the world’s fastest-growing major economies over the next decade.
Managers also highlight:
- improving corporate governance
- expanding capital markets
- increasing retail participation
- digital payment leadership
Optimistic views
Ashoka India Equity Investment Trust (LON:AIE) manager White Oak Capital continues emphasising high-quality companies with sustainable cash generation and strong governance rather than simply chasing rapid growth.
India portfolio managers argue India’s combination of favourable demographics, rising domestic consumption, government reforms and manufacturing investment continues to support long-term earnings growth despite periodic market corrections.
JPMorgan India Growth & Income (LON:JIGI) portfolio managers have consistently argued:
‘India is benefiting from powerful structural tailwinds including formalisation of the economy, digitalisation and increasing financial inclusion.’
They also highlight domestic household savings increasingly flowing into equities as an important long-term support for valuations.
Stewart Investors, which runs India-facing OEICs rather than trusts, has frequently described India as:
‘One of the few emerging markets where we continue to find a deep pipeline of high-quality businesses.’
However, the team stresses valuation discipline remains critical.
More cautious opinions
Not everyone believes India still deserves its premium valuation.
Common concerns include:
- expensive valuations versus other emerging markets
- slowing earnings momentum
- elevated expectations
- dependence on continued domestic inflows
- geopolitical risks
- higher oil prices hurting India’s trade balance
Bearish perspectives
GMO, Jeremy Grantham’s investment firm, has repeatedly argued that:
‘India remains among the most expensive equity markets globally.’
The firm believes high valuations reduce future expected returns, even if the economy continues growing strongly.
Although overall positive, even White Oak Capital (Ashoka India) has warned:
‘Valuations in certain pockets of the market continue to require careful stock selection.’
Rather than buying the whole market, they have increasingly rotated towards businesses where earnings growth better justifies valuations.
Several analysts argue that after years of exceptional performance, future returns are likely to be lower than investors became accustomed to between 2020 and 2024.
Performance remains impressive over longer periods
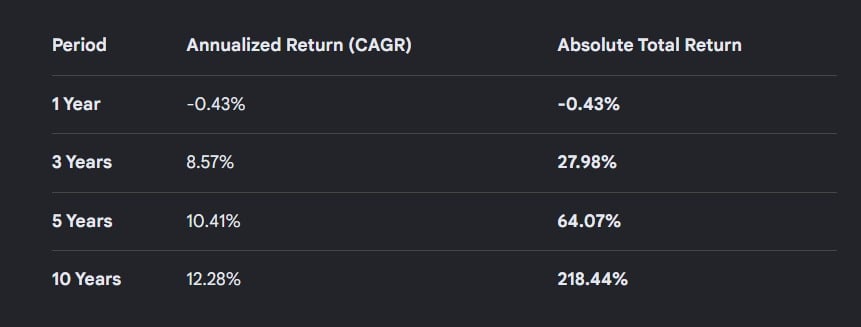
Although recent returns have disappointed, India’s specialist trusts have generally produced excellent long-term results.
Approximate sector performance:*
| Period | Ballpark specialist India trust total return |
| 1 year | Slightly negative to broadly flat |
| 3 years | Around 60-80%* |
| 5 years | Around 80-130%* |
| 10 years | Frequently above 150%* |
*Indictive performance via Google Finance, guidance only
Performance varies considerably between managers, with smaller-company specialists often producing the strongest long-term returns but also experiencing greater volatility.
Have discounts widened?
Yes.
One consequence of weaker sentiment has been wider discounts across much of the sector.
Recent trends include:
- India Capital Growth: around a double-digit discount after previously trading much tighter.
- Aberdeen New India: discounts have remained in the high single digits.
- JPMorgan India Growth & Income: typically around a mid-single-digit discount.
- Ashoka India Equity: continues to trade relatively close to NAV thanks to strong demand and active capital management.
While widening discounts can be frustrating, they may also present opportunities for long-term investors if sentiment improves.
Which trust suits which investor?
| Trust | Primary objective | Best suited for |
| JPMorgan India Growth & Income | Long-term capital growth plus a regular income policy | Investors wanting broad Indian exposure with some income |
| Ashoka India Equity | High-quality companies with sustainable growth | Long-term growth investors seeking lower portfolio turnover |
| Aberdeen New India | Active all-cap exposure across India’s economy | Investors comfortable with higher volatility for long-term returns |
| India Capital Growth | Smaller and mid-sized Indian businesses | Higher-risk investors seeking maximum capital growth |
| Templeton Emerging Markets | Diversified emerging markets with India as a major allocation | Investors wanting broader EM diversification rather than a pure India bet |
| JPMorgan Emerging Markets | Large diversified emerging-market portfolio | Investors building a global emerging markets allocation |
Bull vs bear case for India investment trusts
| 🐂 Bull case | 🐻 Bear case |
| Structural growth story remains intact. India is still expected to be one of the fastest-growing major economies over the next decade, supported by favourable demographics, urbanisation and rising incomes. | Valuations remain demanding. Even after the recent pullback, many Indian companies continue to trade at a premium to other emerging markets, leaving less room for disappointment. |
| Domestic demand is resilient. A growing middle class, expanding financial services sector and rising consumer spending provide a powerful engine for corporate earnings. | Earnings growth could slow. Corporate profits may struggle to justify premium valuations if economic growth moderates or margins come under pressure. |
| Manufacturing shift from China. Global companies diversifying supply chains could continue directing investment into Indian manufacturing, infrastructure and technology. | Foreign investor outflows. India has relied heavily on overseas capital. Higher US interest rates or a stronger dollar could trigger further selling by international investors. |
| Healthy market reset. The consolidation from late 2024 through early 2026 has reduced some of the excesses built up during the previous bull market, potentially creating a better entry point for long-term investors. | Geopolitical and commodity risks. India remains vulnerable to higher oil prices, regional tensions and global trade disruptions, all of which could weigh on growth and investor sentiment. |
| Investment trust discounts have widened. Wider discounts to NAV may offer additional upside if sentiment improves and discounts narrow back towards historical averages. | Discounts may stay wide. If investors continue to favour developed markets or AI-related US technology stocks, India-focused trusts could remain out of favour for an extended period. |
| Long-term track record. India specialist investment trusts have generated some of the strongest total returns in the UK investment trust universe over five and ten years, despite periods of volatility. | Higher volatility. India remains an emerging market, meaning investors should expect larger share price swings, particularly in trusts with significant exposure to mid- and small-cap companies. |
Investor verdict
India has been one of the world’s best-performing major equity markets over the past decade, but the investment case has clearly become more challenging after several years of exceptional returns. Elevated valuations have moderated, foreign inflows have slowed and investment trust discounts have widened.
Yet many professional investors argue the long-term structural story remains intact. Rising domestic consumption, manufacturing expansion, infrastructure investment and favourable demographics continue to distinguish India from many other emerging markets.
Research the AIC website for India trusts
For UK investors with a 5–10-year investment horizon, today’s wider discounts may prove more attractive than the near-premium valuations seen during the market’s strongest years. However, investors should expect continued volatility, particularly among smaller-company trusts, and avoid assuming the extraordinary gains delivered between 2022 and 2024 will be repeated at the same pace.
You might also like:

Investment company news brought to you by Sharesify.


